A Quarter Review
Fixed income markets faced a challenging third quarter as rising geopolitical tensions, including the conflict with Iran, contributed to higher oil prices and renewed inflation concerns. Against this backdrop, the Federal Reserve delivered its first rate hike in several years and signaled its intention to raise rates at least one more time this year. Treasury yields moved higher across the curve, pushing rates to multi-decade highs and weighing on bond returns.
Credit fundamentals remained generally solid, but modest spread widening added to market pressure. Investment-grade corporate spreads widened 6 basis points and outperformed mortgage-backed securities, where spreads widened 19 basis points and excess returns lagged.
Performance Summary
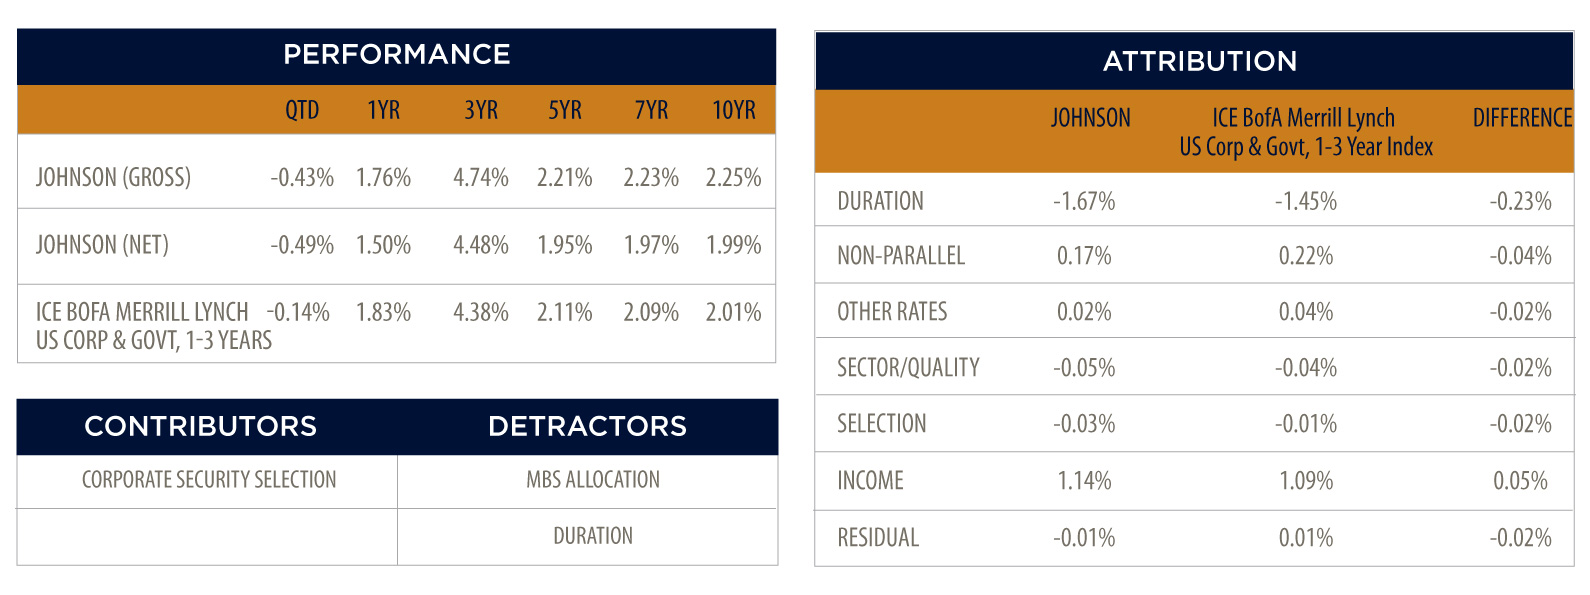
The Johnson Short Duration Fixed Income Strategy returned -0.49% net of fees during the third quarter, compared to -0.14% for the ICE BofAML US Corp & Government 1-3 Year index. The primary driver of relative underperformance was the Strategy's longer duration positioning as interest rates moved sharply higher across the yield curve. Additionally, the Strategy’s out-of-benchmark allocation to mortgage-backed securities was a further drag on relative performance as MBS spreads widened during the quarter.
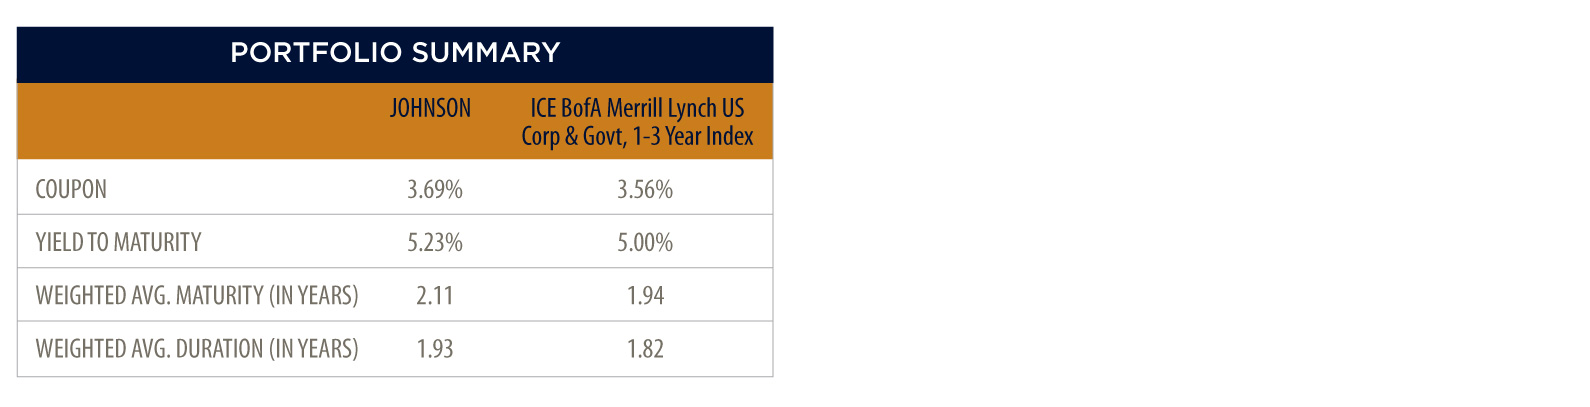
While the duration and MBS allocation detracted from relative performance during the third quarter, security selection within corporates was a modestly positive contribution against investment-grade spread widening during the quarter. In addition, the Strategy’s income advantage compared to its benchmark also contributed positively to relative returns.
Market Outlook and Portfolio Positioning
Bond yields remain near their highest levels in nearly two decades, creating an attractive starting point for long-term investors. While inflation, economic growth, Federal Reserve policy, geopolitical tensions, and fiscal concerns continue to create uncertainty, current yields provide a meaningful cushion against a range of potential outcomes. We continue to maintain a modest duration overweight, primarily as a counterbalance to somewhat higher credit weight.
While spreads remain tight, improving economic fundamentals support a modestly higher corporate weight within portfolios. We still view portfolios as conservatively positioned but no longer remain at the very low end of our target range for credit weight. The team also added to maintain our Agency MBS allocation throughout the quarter as recent underperformance of the sector pointed to increasingly attractive valuations.
Looking ahead, the path for monetary policy remains uncertain. Inflation has become increasingly influenced by supply-side factors, particularly energy prices, while labor market data has softened but remains uneven. The good news for investors is that today’s higher yields provide a much stronger income cushion than has been available in years. While volatility may persist in the near term, the bond market now offers some of the most attractive long-term return potential seen in over a decade.
Our primary objective across all duration mandates is to outperform the market with comparable volatility by utilizing our proprietary and unique Quality Yield approach and the deep experience and continuity of our investment team. For more information on our products and services, please contact a member of our Sales & Client Service Team at 513.389.2770 or info@johnsonasset.com.
Published 11/06/2026
The BofA Merrill Lynch US Corp & Govt. 1-3 year index is unmanaged, does not reflect the deduction of fees, transaction costs, or other expenses, and cannot be invested in directly. Index returns assume reinvestment of income. The index is shown for comparison only; the Strategy's holdings, sector weights, duration, and credit quality differ from the index, so its performance and volatility may differ materially. The commentary contains the opinions of Johnson Asset Management's investment team as of September 30, 2026. These opinions may change without notice and should not be read as investment advice or a recommendation to buy or sell any security or sector. Statements about the market outlook, interest rates, inflation, monetary policy, yields, or future return potential are forward-looking. They are based on current expectations and assumptions that may prove wrong, and actual results may differ materially. Higher current yields do not guarantee future returns. Bond prices generally fall when interest rates rise, and fixed income investments are subject to interest rate, credit, prepayment, and liquidity risk. Portfolio characteristics and positioning shown are as of the date noted and may change without notice. Johnson Asset Management (JAM) is a division of Johnson Investment Counsel, Inc. (“JIC”), an independent and privately owned Midwestern-based investment advisory firm registered with the Securities and Exchange Commission. Johnson Asset Management manages institutional separate account portfolios for a wide variety of for-profit and non-profit organizations, public agencies, public and private retirement plans, and personal trusts of all sizes. It may also serve as sub-adviser for mutual funds. JIC’s fees are available upon request and may be found in our Form ADV Part 2A. Performance data quoted herein represents past performance. Past performance does not guarantee or indicate future results. All data is current as of September 30, 2026 unless otherwise noted. Returns and net asset value will fluctuate. To determine if this strategy is appropriate for you, carefully consider the investment objectives, risk factors, and expenses before investing. Individual account management and construction will vary depending on each client's investment needs and objectives. Investments employing JIC’s strategies are NOT insured by the FDIC or by any other Federal Government Agency, are NOT Bank deposits, are NOT guaranteed by any Bank or any Bank affiliate, and MAY lose value, including possible loss of principal. Johnson Asset Management claims compliance with the Global Investment Performance Standards. The Short Duration Fixed Income composite includes all fee-paying, fully discretionary, actively managed institutional fixed income portfolios with a minimum value of $500,000 and an investment objective of short duration, investment grade taxable fixed income. The benchmark for this composite is the ICE BofA Merrill Lynch 1-3 Year G/C Index. The ICE BofA Merrill Lynch 1-3 Year Corporate/Government Bond Index includes publicly issued U.S. Treasury debt, U.S. government agency debt, taxable debt issued by U.S. states and territories and their political subdivisions, debt issued by U.S. and non-U.S. corporations, non-U.S. government debt and supranational debt. GIPS® is a registered trademark of CFA Institute. CFA Institute does not endorse or promote this organization, nor does it warrant the accuracy or quality of the content contained herein. JAM’s policies for valuing portfolios, calculating performance and preparing compliant presentations, as well as a complete list of composite descriptions are available upon request. Please contact our office at 513.389.2770 or 3777 West Fork Road, Cincinnati, OH 45247. All returns reflect the reinvestment of investment income (dividends and/or interest) and capital gains. Valuations and returns are stated in U.S. dollars. Trade date accounting is used. Portfolio returns are calculated using time weighed return methodology on a monthly basis. Net returns shown reflect gross performance less the highest fee schedule for this strategy. Actual client returns would also be reduced by brokerage commissions, custodial fees, and other client paid expenses detailed in JIC’s Form ADV Part 2A.